Making local payment methods easier to discover, use, and manage across markets
I led two connected changes to the OKX payment experience:
- Moving payment discovery from first-time deposit to first-time trade
- Redesigning how users select and manage methods inside Deposit
- Role
- Lead product designer
- Markets
- U.S., Europe, UAE, Australia, Brazil, and Asia
- Scope
- Payment onboarding, funding, payment selection, checkout, account states, and account management
- Outcome
- Apple Pay usage increased 3×. First-time card trades increased 60% within one month.
Part one
Making local payment methods easier to discover and use
Users could reach Buy faster by leaving onboarding than by completing it
The first-time deposit flow asked users to add a payment method before buying. But Apple Pay was already available in Buy and required no setup.
A user who left onboarding could go directly to Buy and pay with Apple Pay.
A user who followed the flow first added a card or linked an account, then continued on to make a deposit. After returning to Buy, they had three ways to pay: their balance, the method they had just added, or Apple Pay / Google Pay.
The new method was still useful, but it was not required for the user’s immediate goal. Following the recommended path created more work than leaving it.
This exposed the mismatch: onboarding was organized around funding the account, while many users simply wanted to make their first trade.
Leave onboarding
Complete onboarding
FTT (first-time trade) kept Deposit available without choosing the payment path for users
Growing assets under management was a business goal, and directing new users to Deposit supported it.
But Deposit did not always match the user’s immediate goal. Someone trying to make a trade could pay directly with a card, wallet, or local bank method.
I proposed moving from first-time deposit to first-time trade. Users started with the trade they wanted to make, then saw the payment options available to them.
Deposit remained an option, but it was no longer the only route presented first. Users could compare methods and choose based on speed, cost, and required setup.
Before
After
New users needed to compare methods and know what happened next
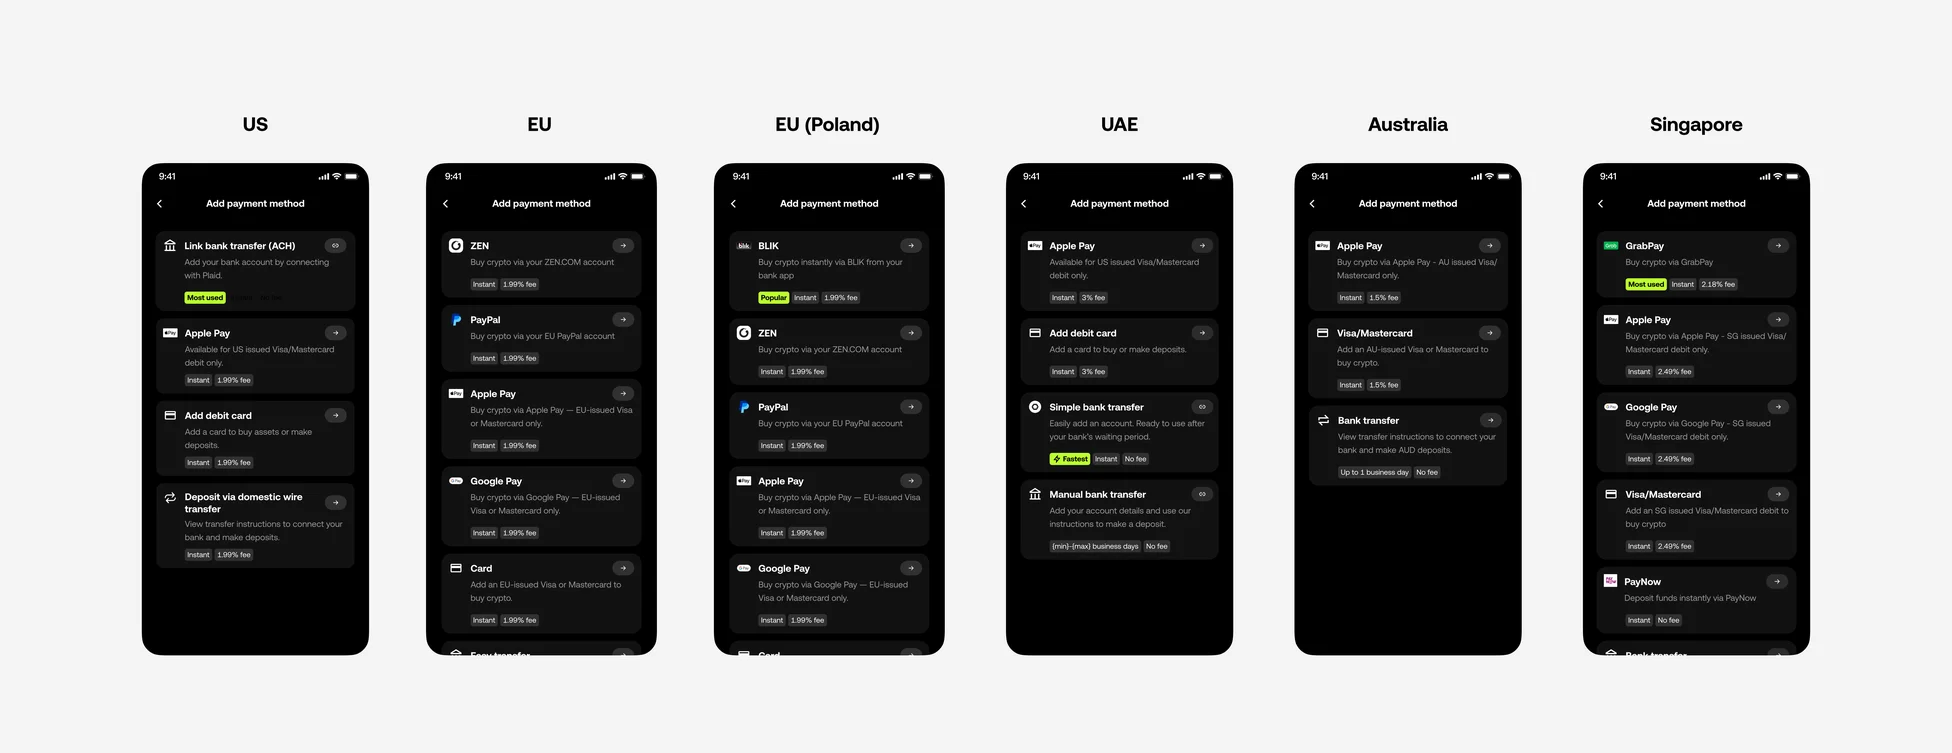
The payment list showed each method’s speed, fee, limit, and required action.
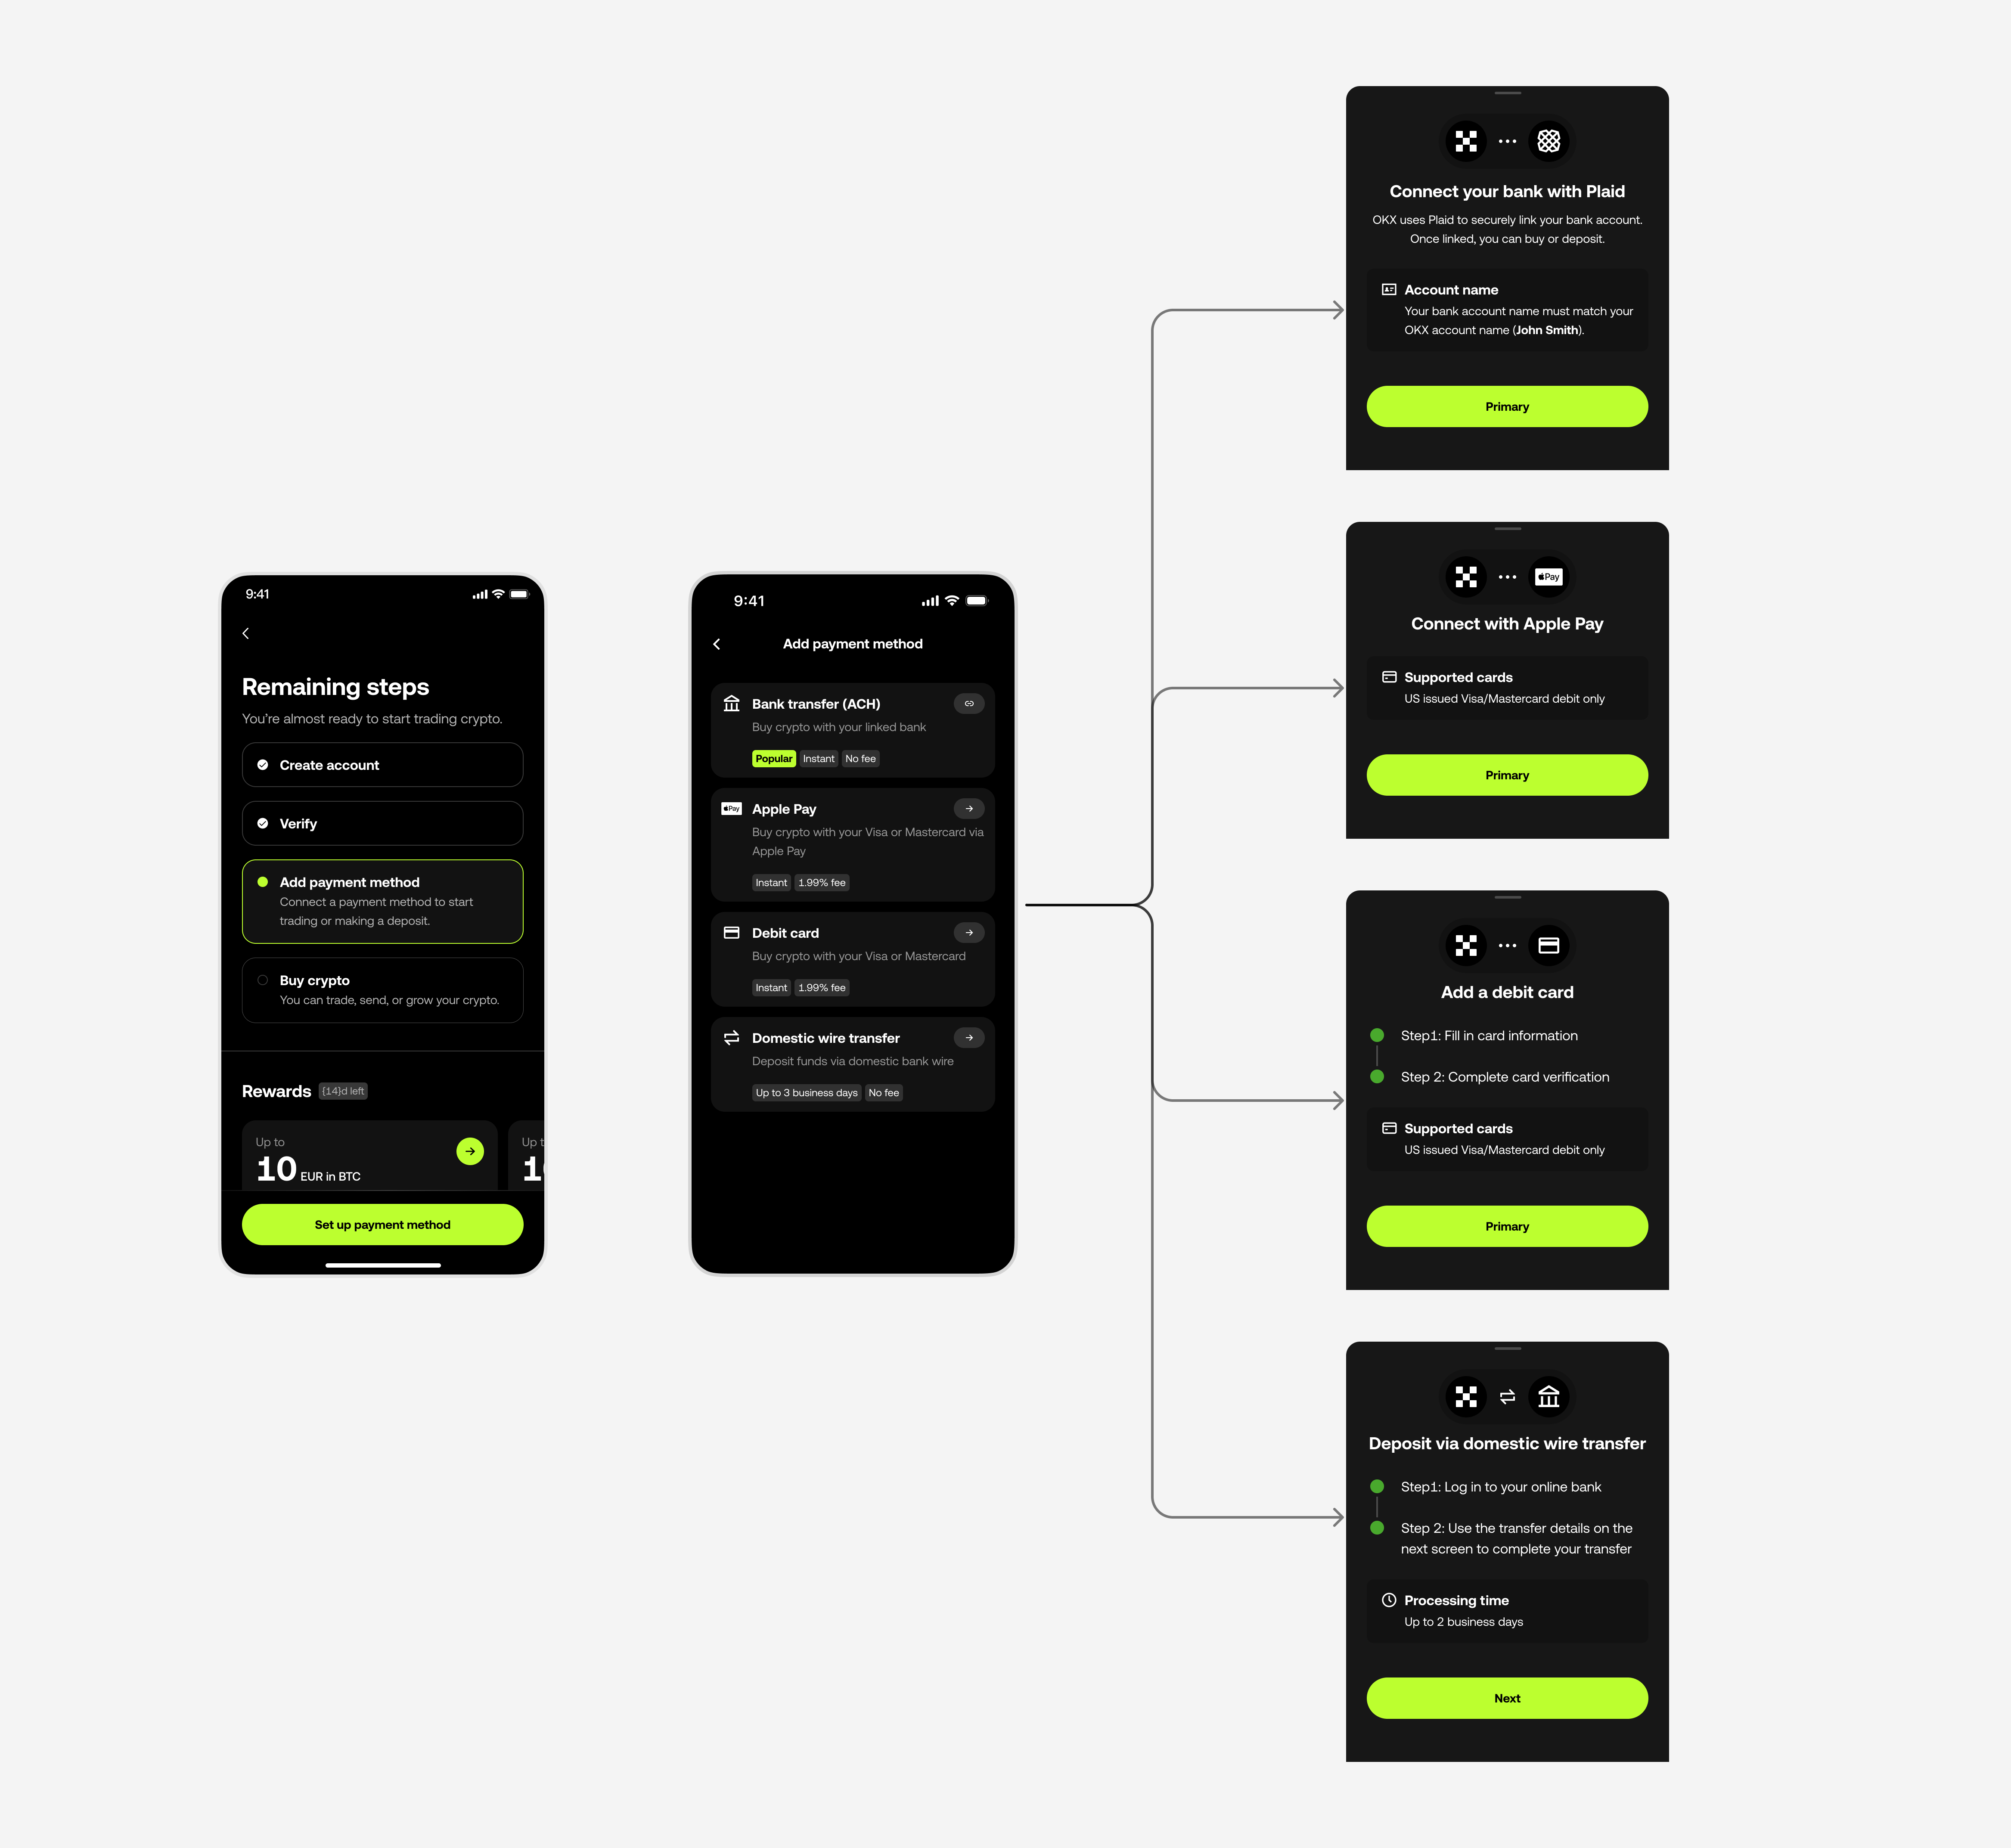
After selection, an interstitial explained the provider handoff, what users needed to prepare, and whether verification or waiting could follow.
Different methods required different steps, so users needed to know what would happen next
ACH required account linking. iDEAL opened another service. Wire transfers required bank instructions. Some methods also included verification or waiting.
I defined what users needed to know before continuing:
- Where they would go next
- What they needed to prepare
- Whether the method was instant
- Fees and limits
- Whether verification or waiting could follow
The payment list supported comparison. An interstitial then explained the next step without repeating the same information.
I built the global framework from the most complex regional flow
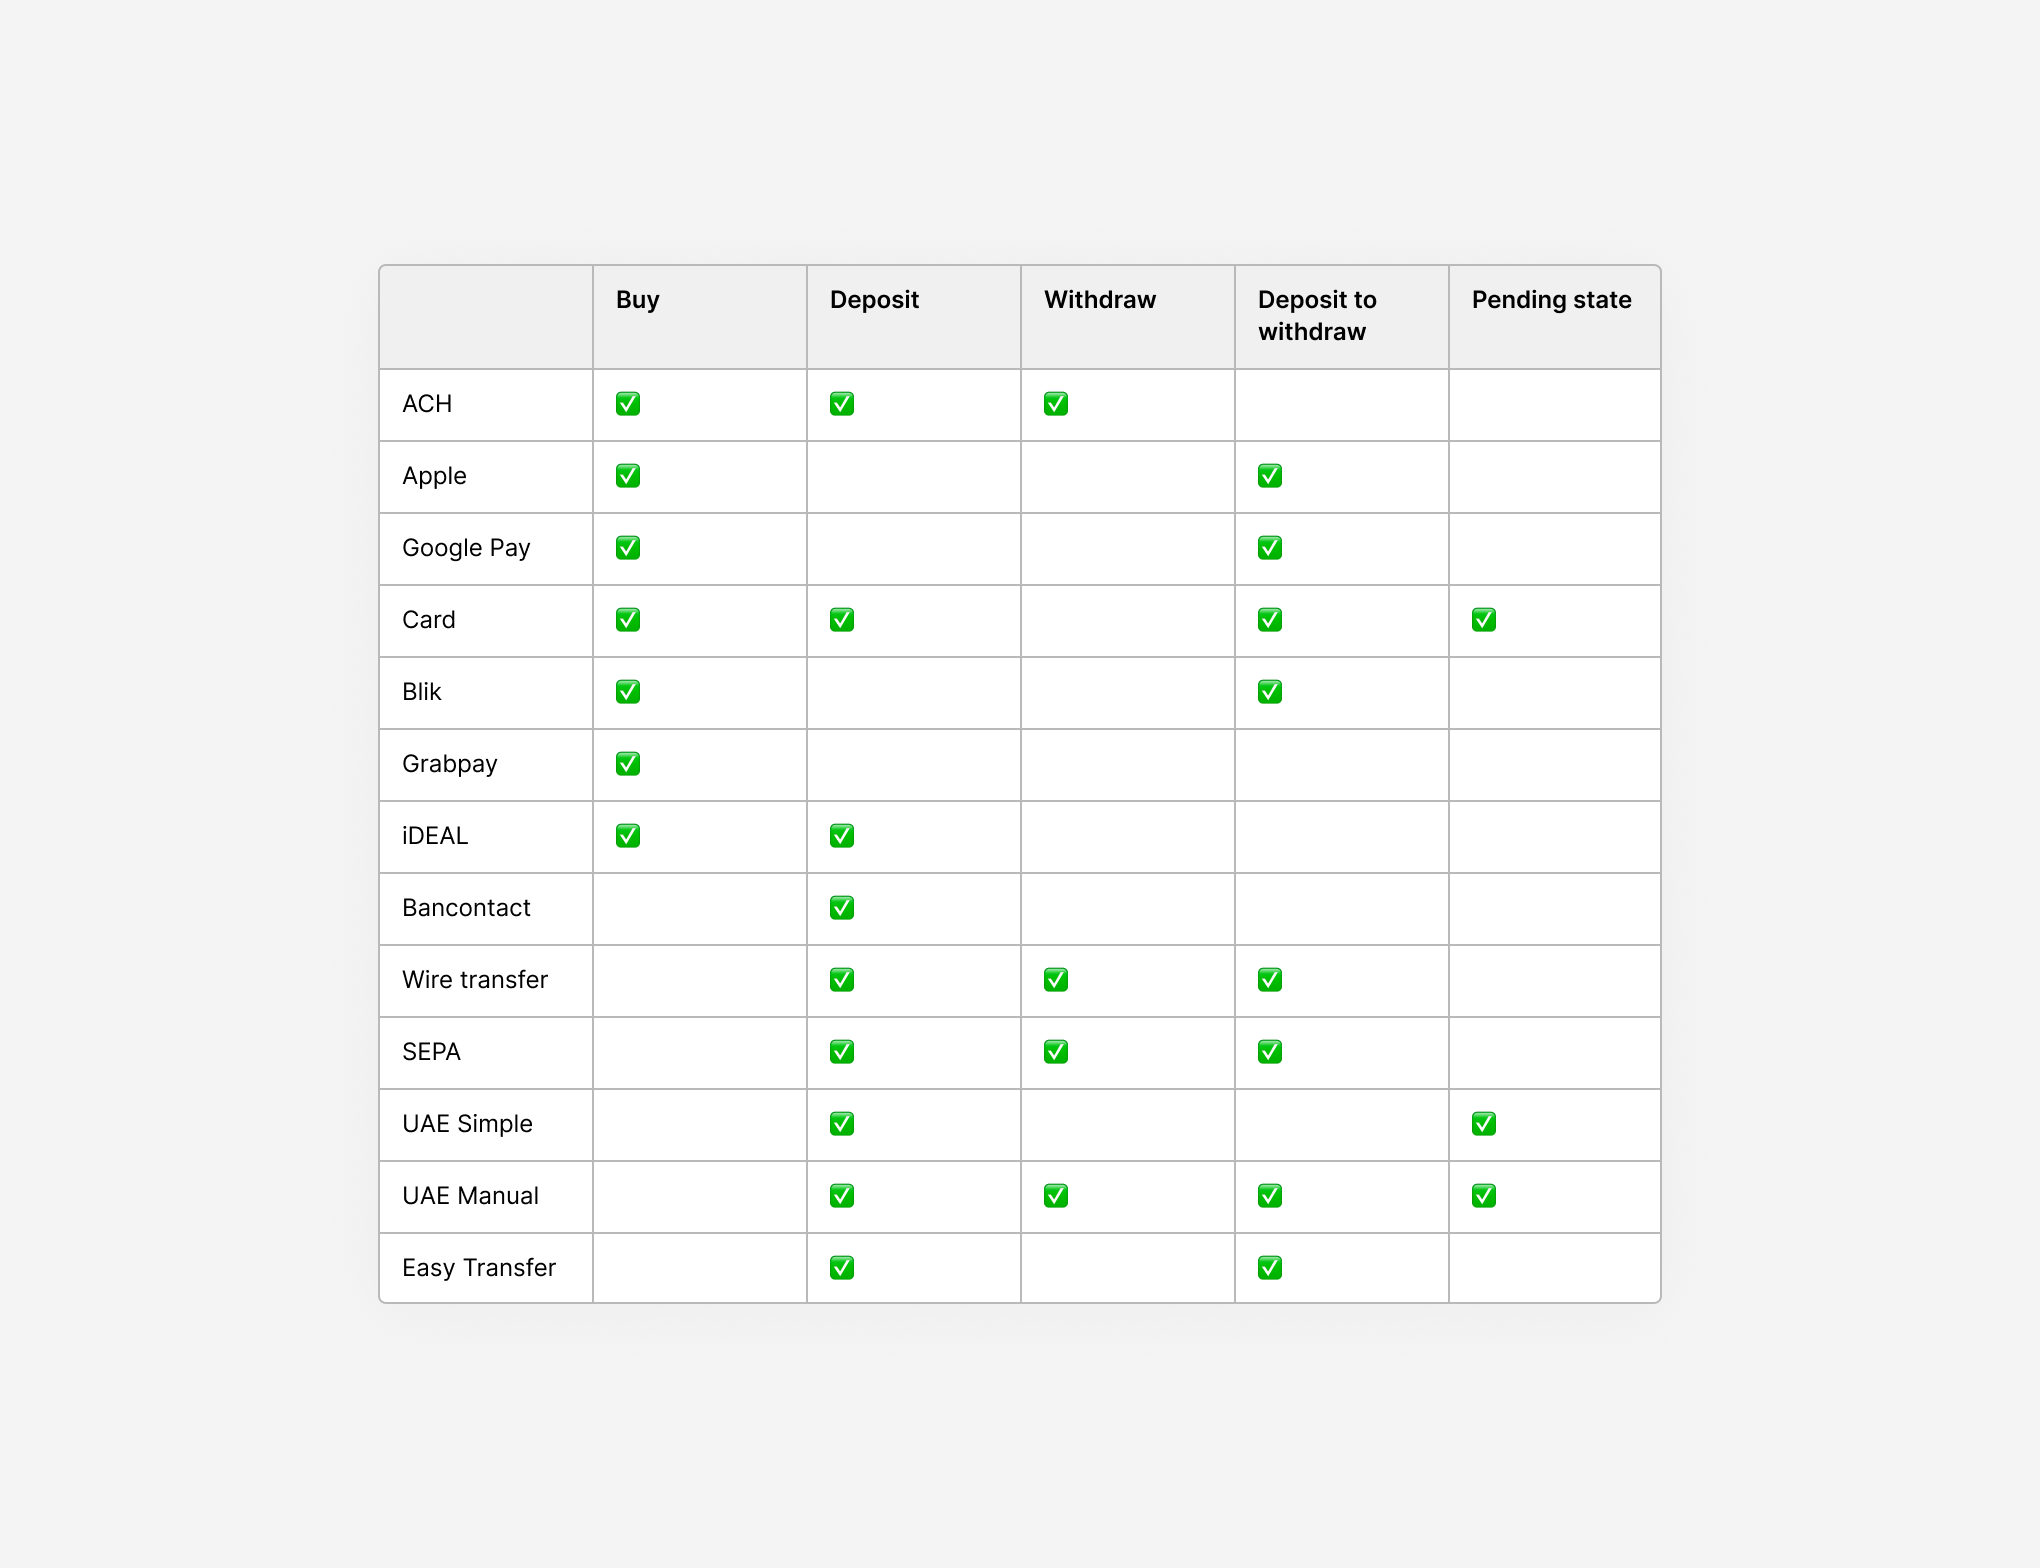
I collected the existing payment flows across markets and used the flow with the most states and exceptions to define the framework.
From there, I separated the shared journey from market-specific rules, tested it against the remaining regions, and turned recurring patterns into reusable components.
This gave each market room to support its own payment methods without creating a different experience from scratch.
Part two
A faster Deposit flow for returning users
Returning users expected to enter an amount, not choose a payment method again.
Returning users had to leave Deposit to switch or manage a method
A separate payment-method screen appeared before the amount page.
Switching methods or managing an account meant leaving Deposit and navigating back.
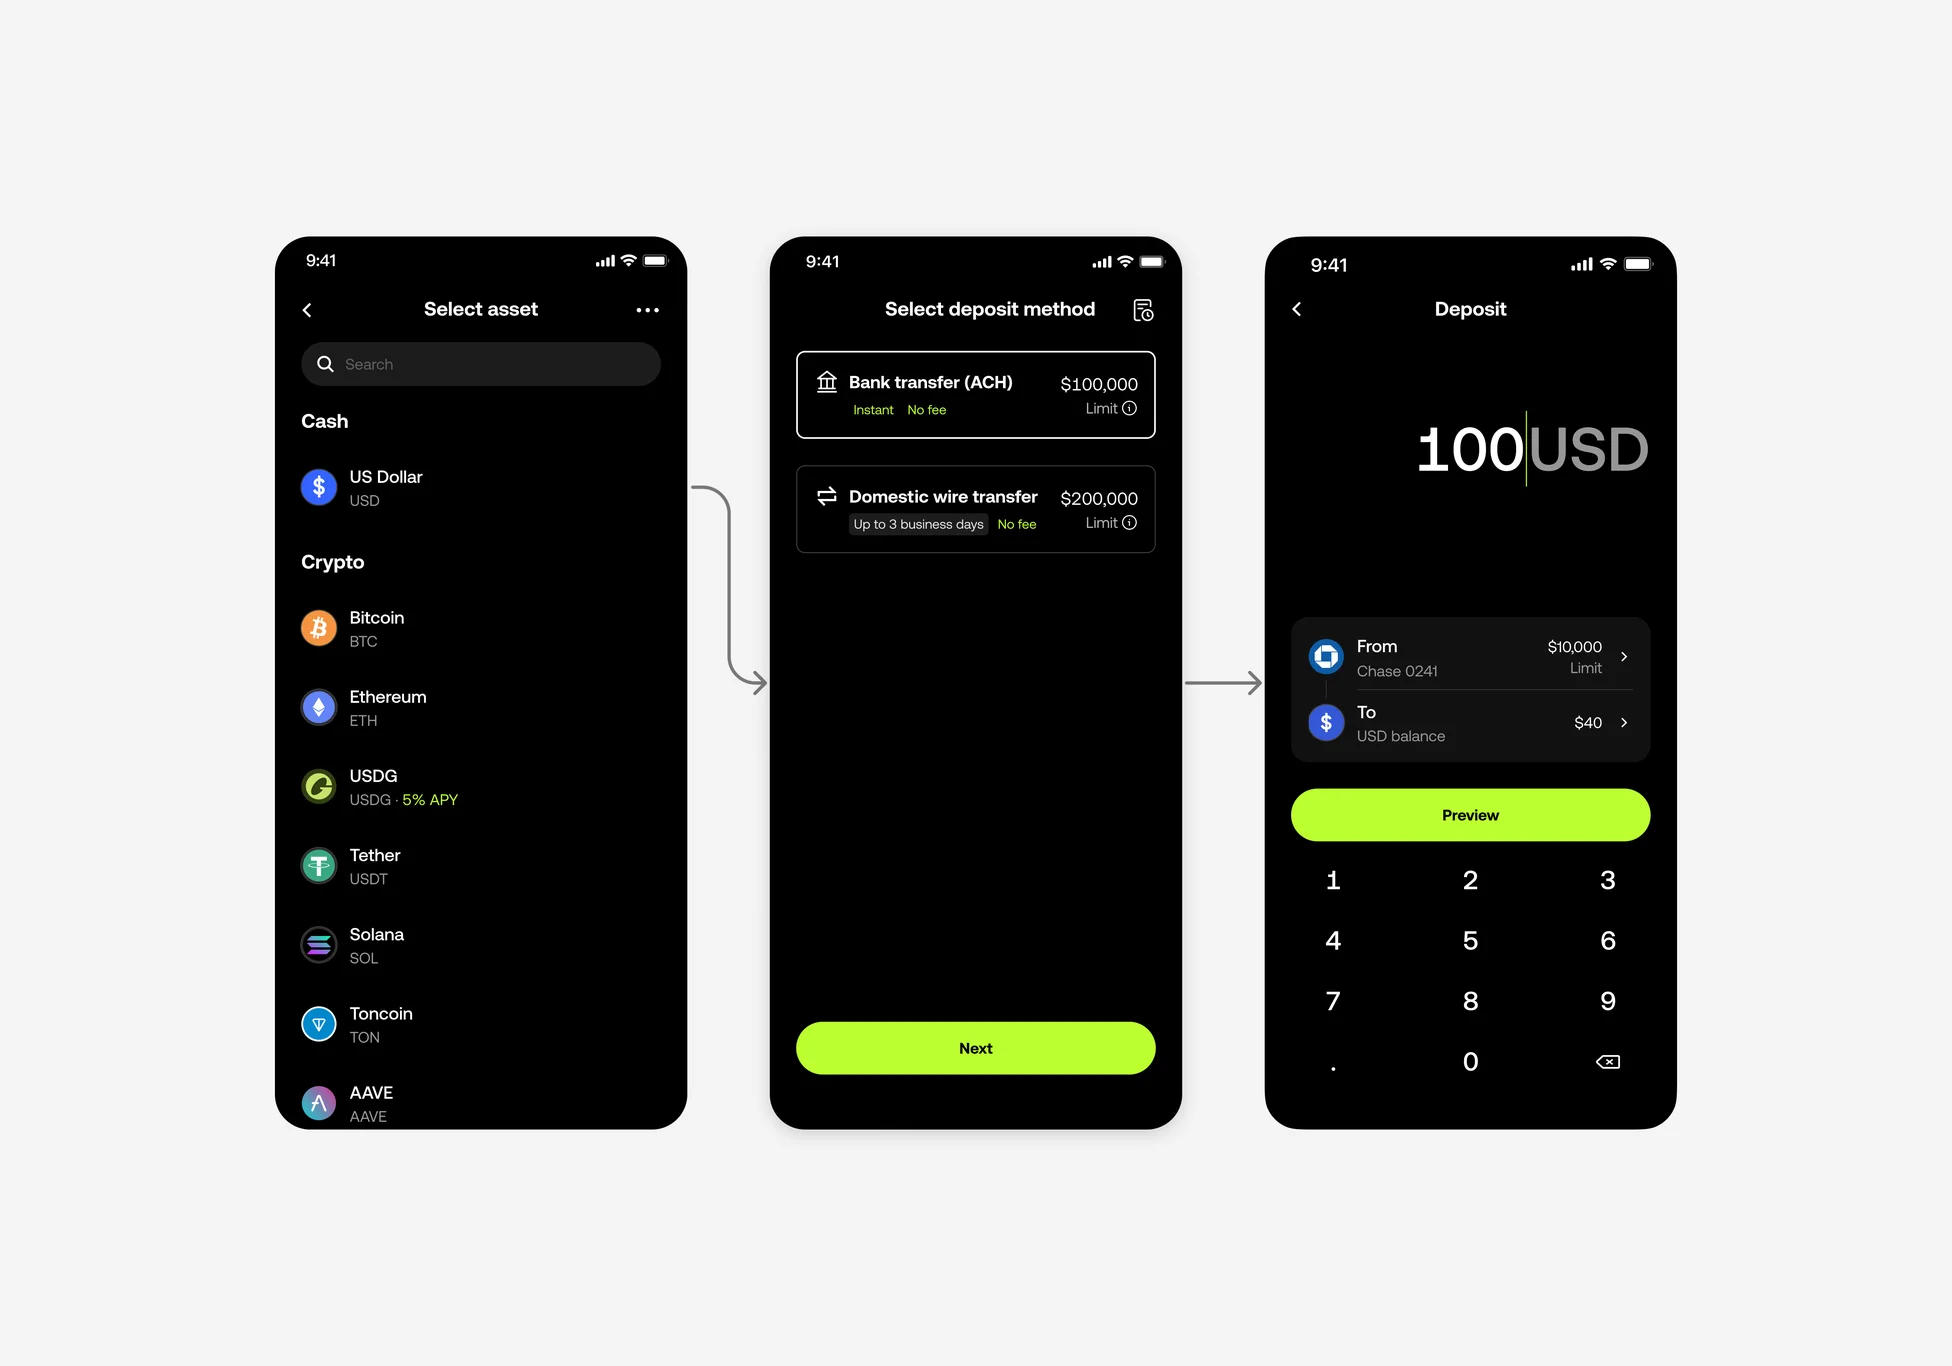
I removed the middle screen and brought payment management into Deposit
Deposit now opened on the amount page with an account selected.
Tapping the account opened a sheet where users could switch, add, manage, or check the status of payment methods.
The same structure could be reused across markets while preserving each method’s required steps.
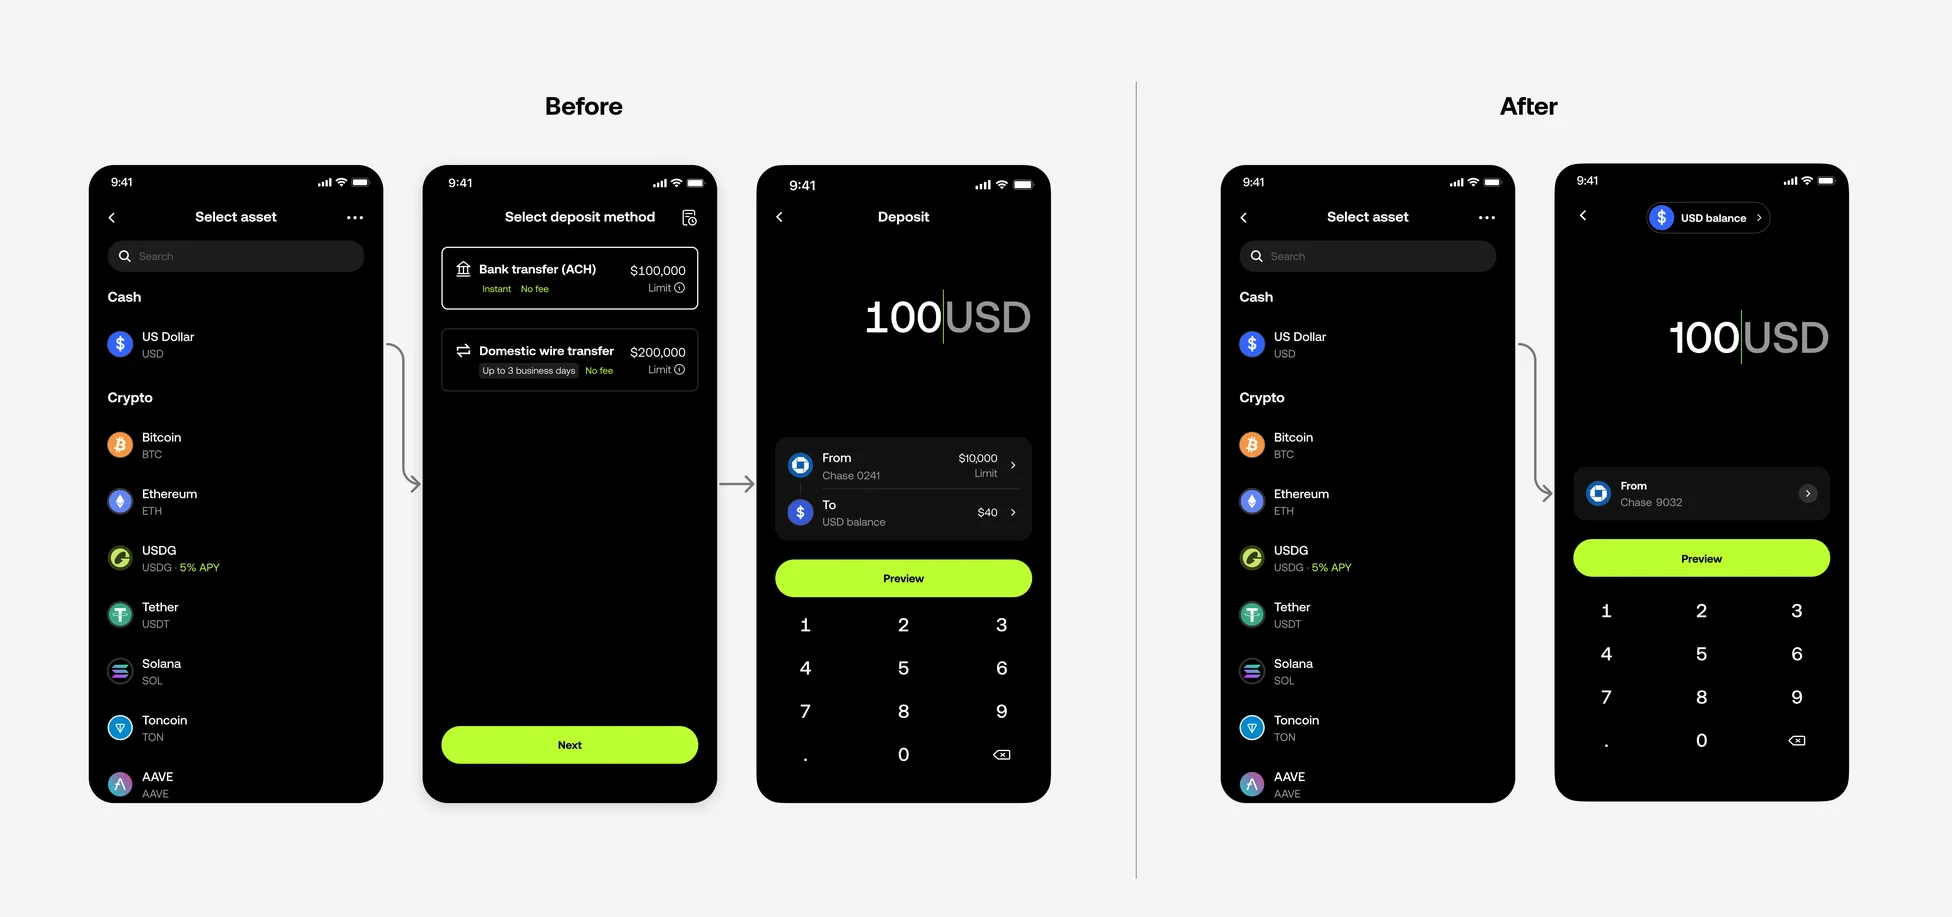
The payment sheet showed what was ready and what required another step
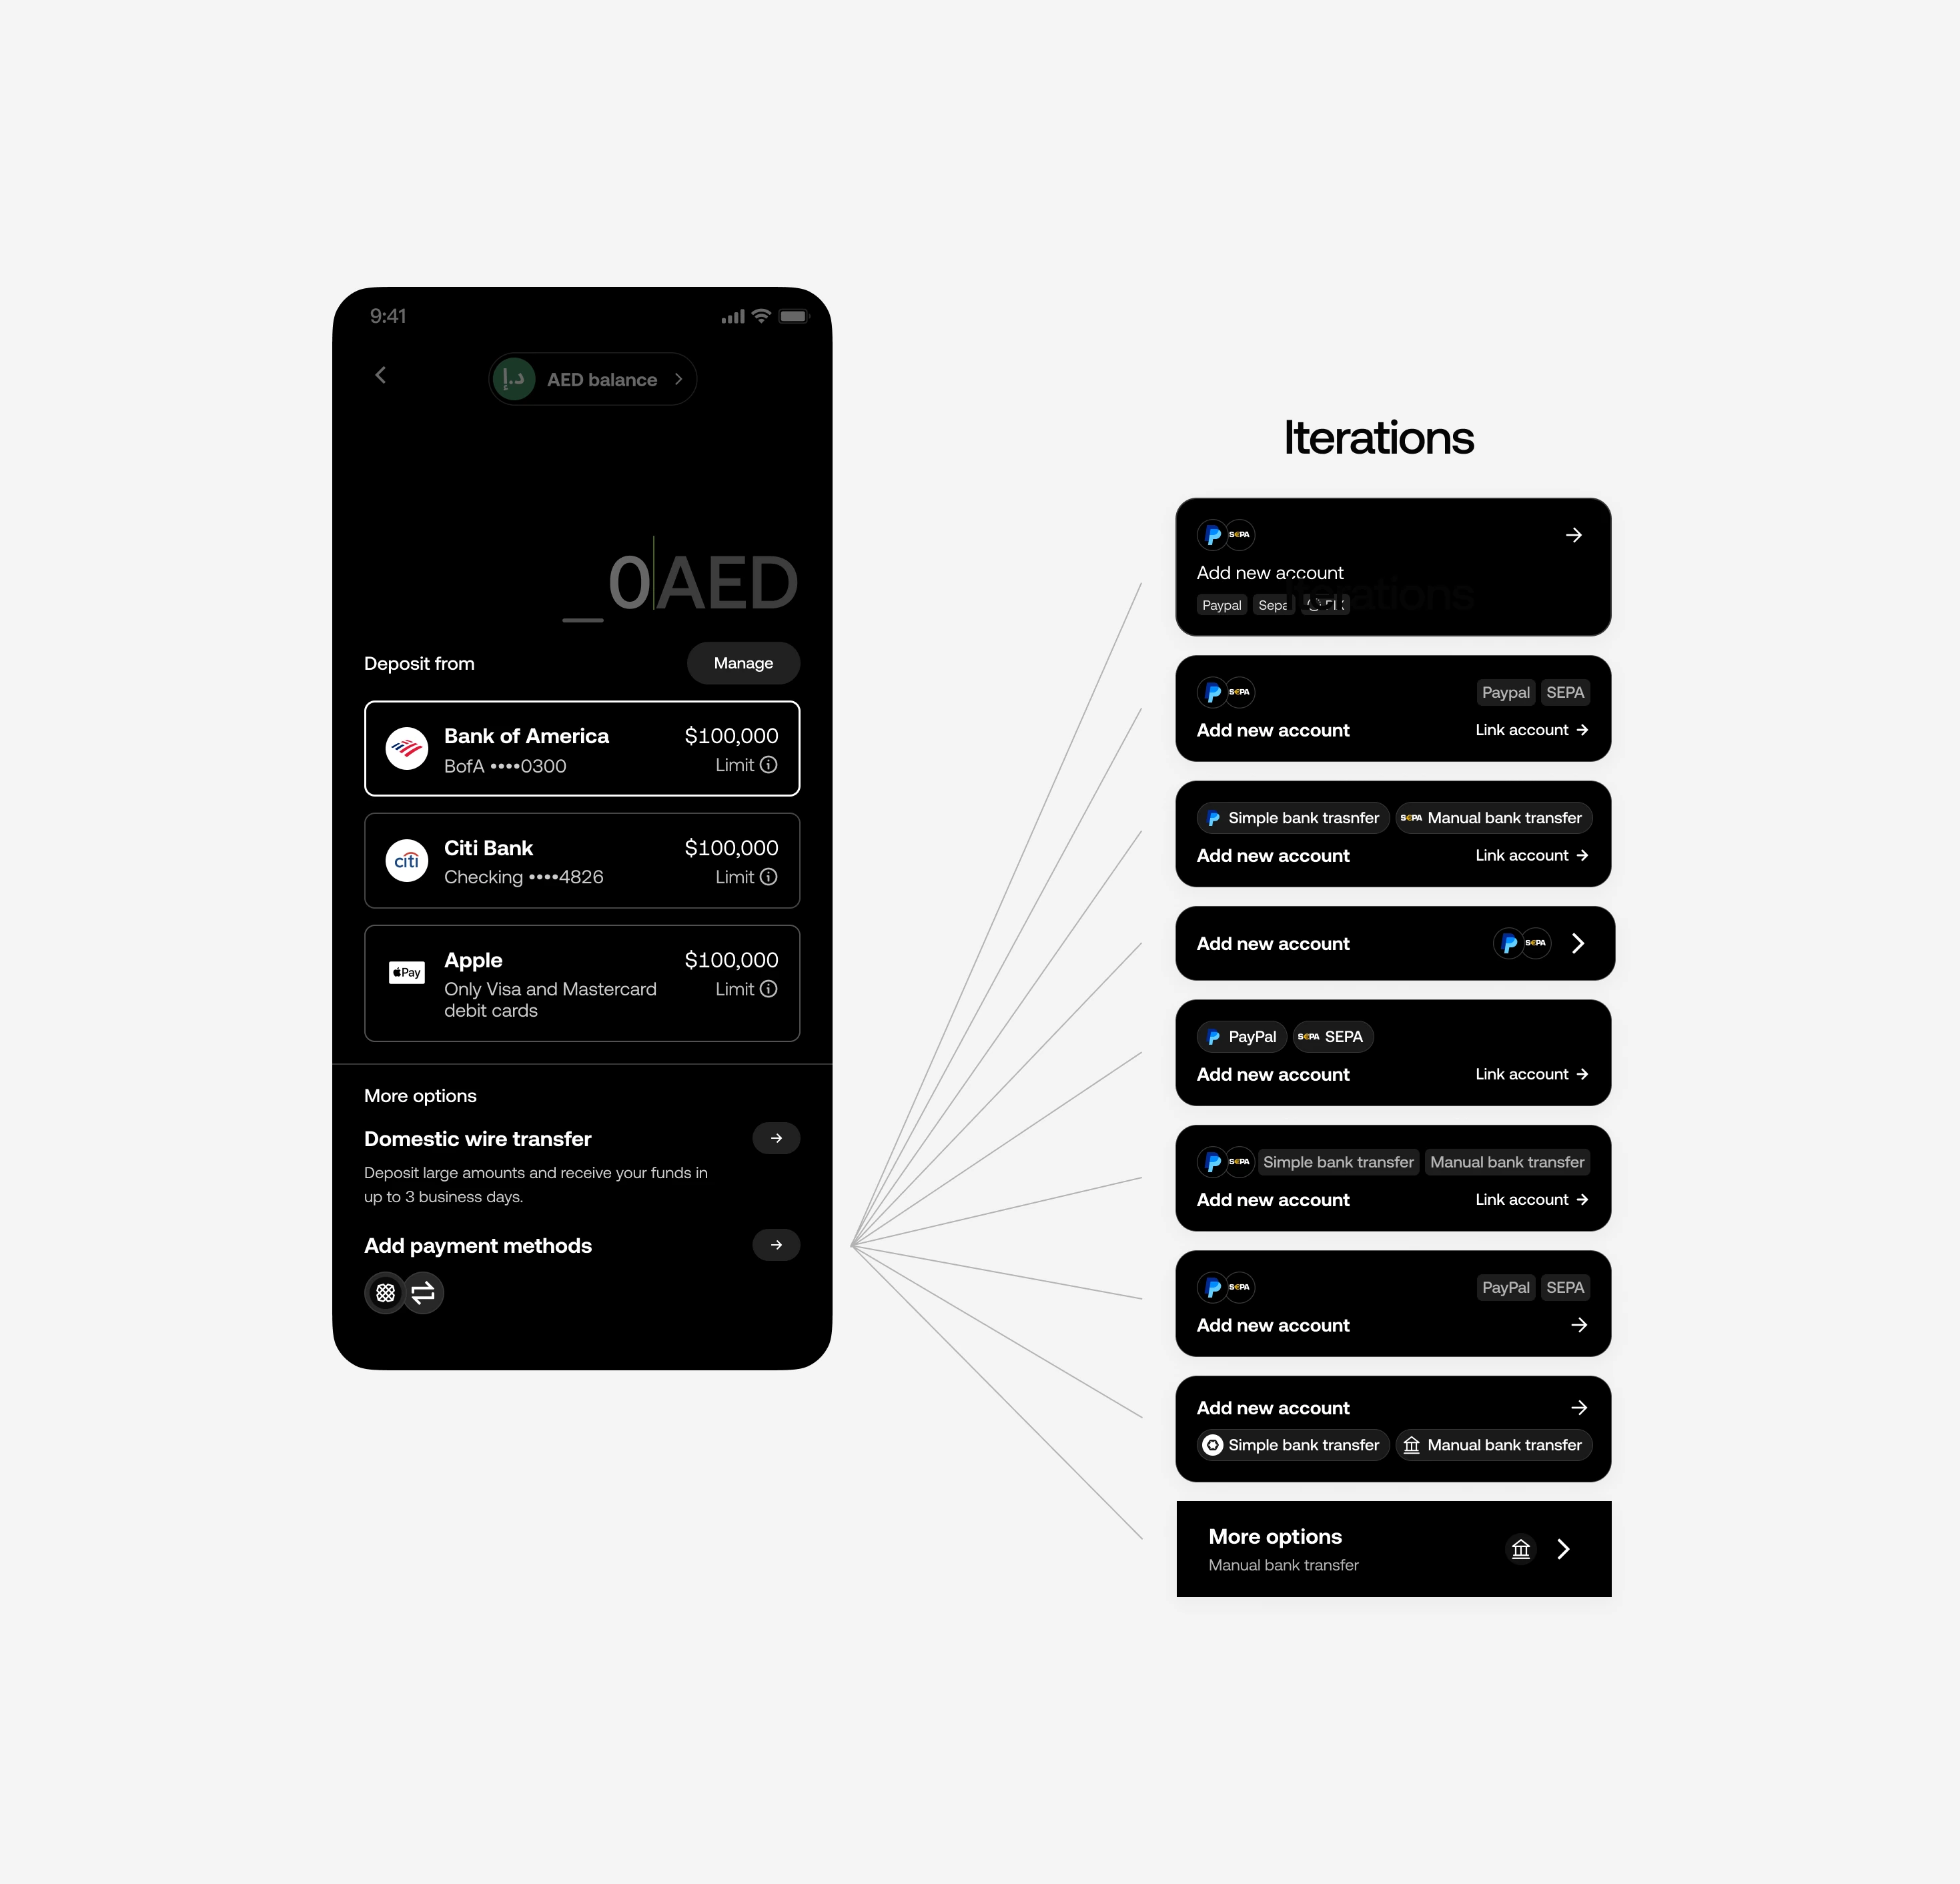
I grouped methods by what happened after selection:
- Ready accounts — select and deposit
- View instructions — open manual transfer or wire details
- Add payment methods — view icons for methods requiring setup
The grouping reduced unnecessary taps and made available payment options easier to scan.
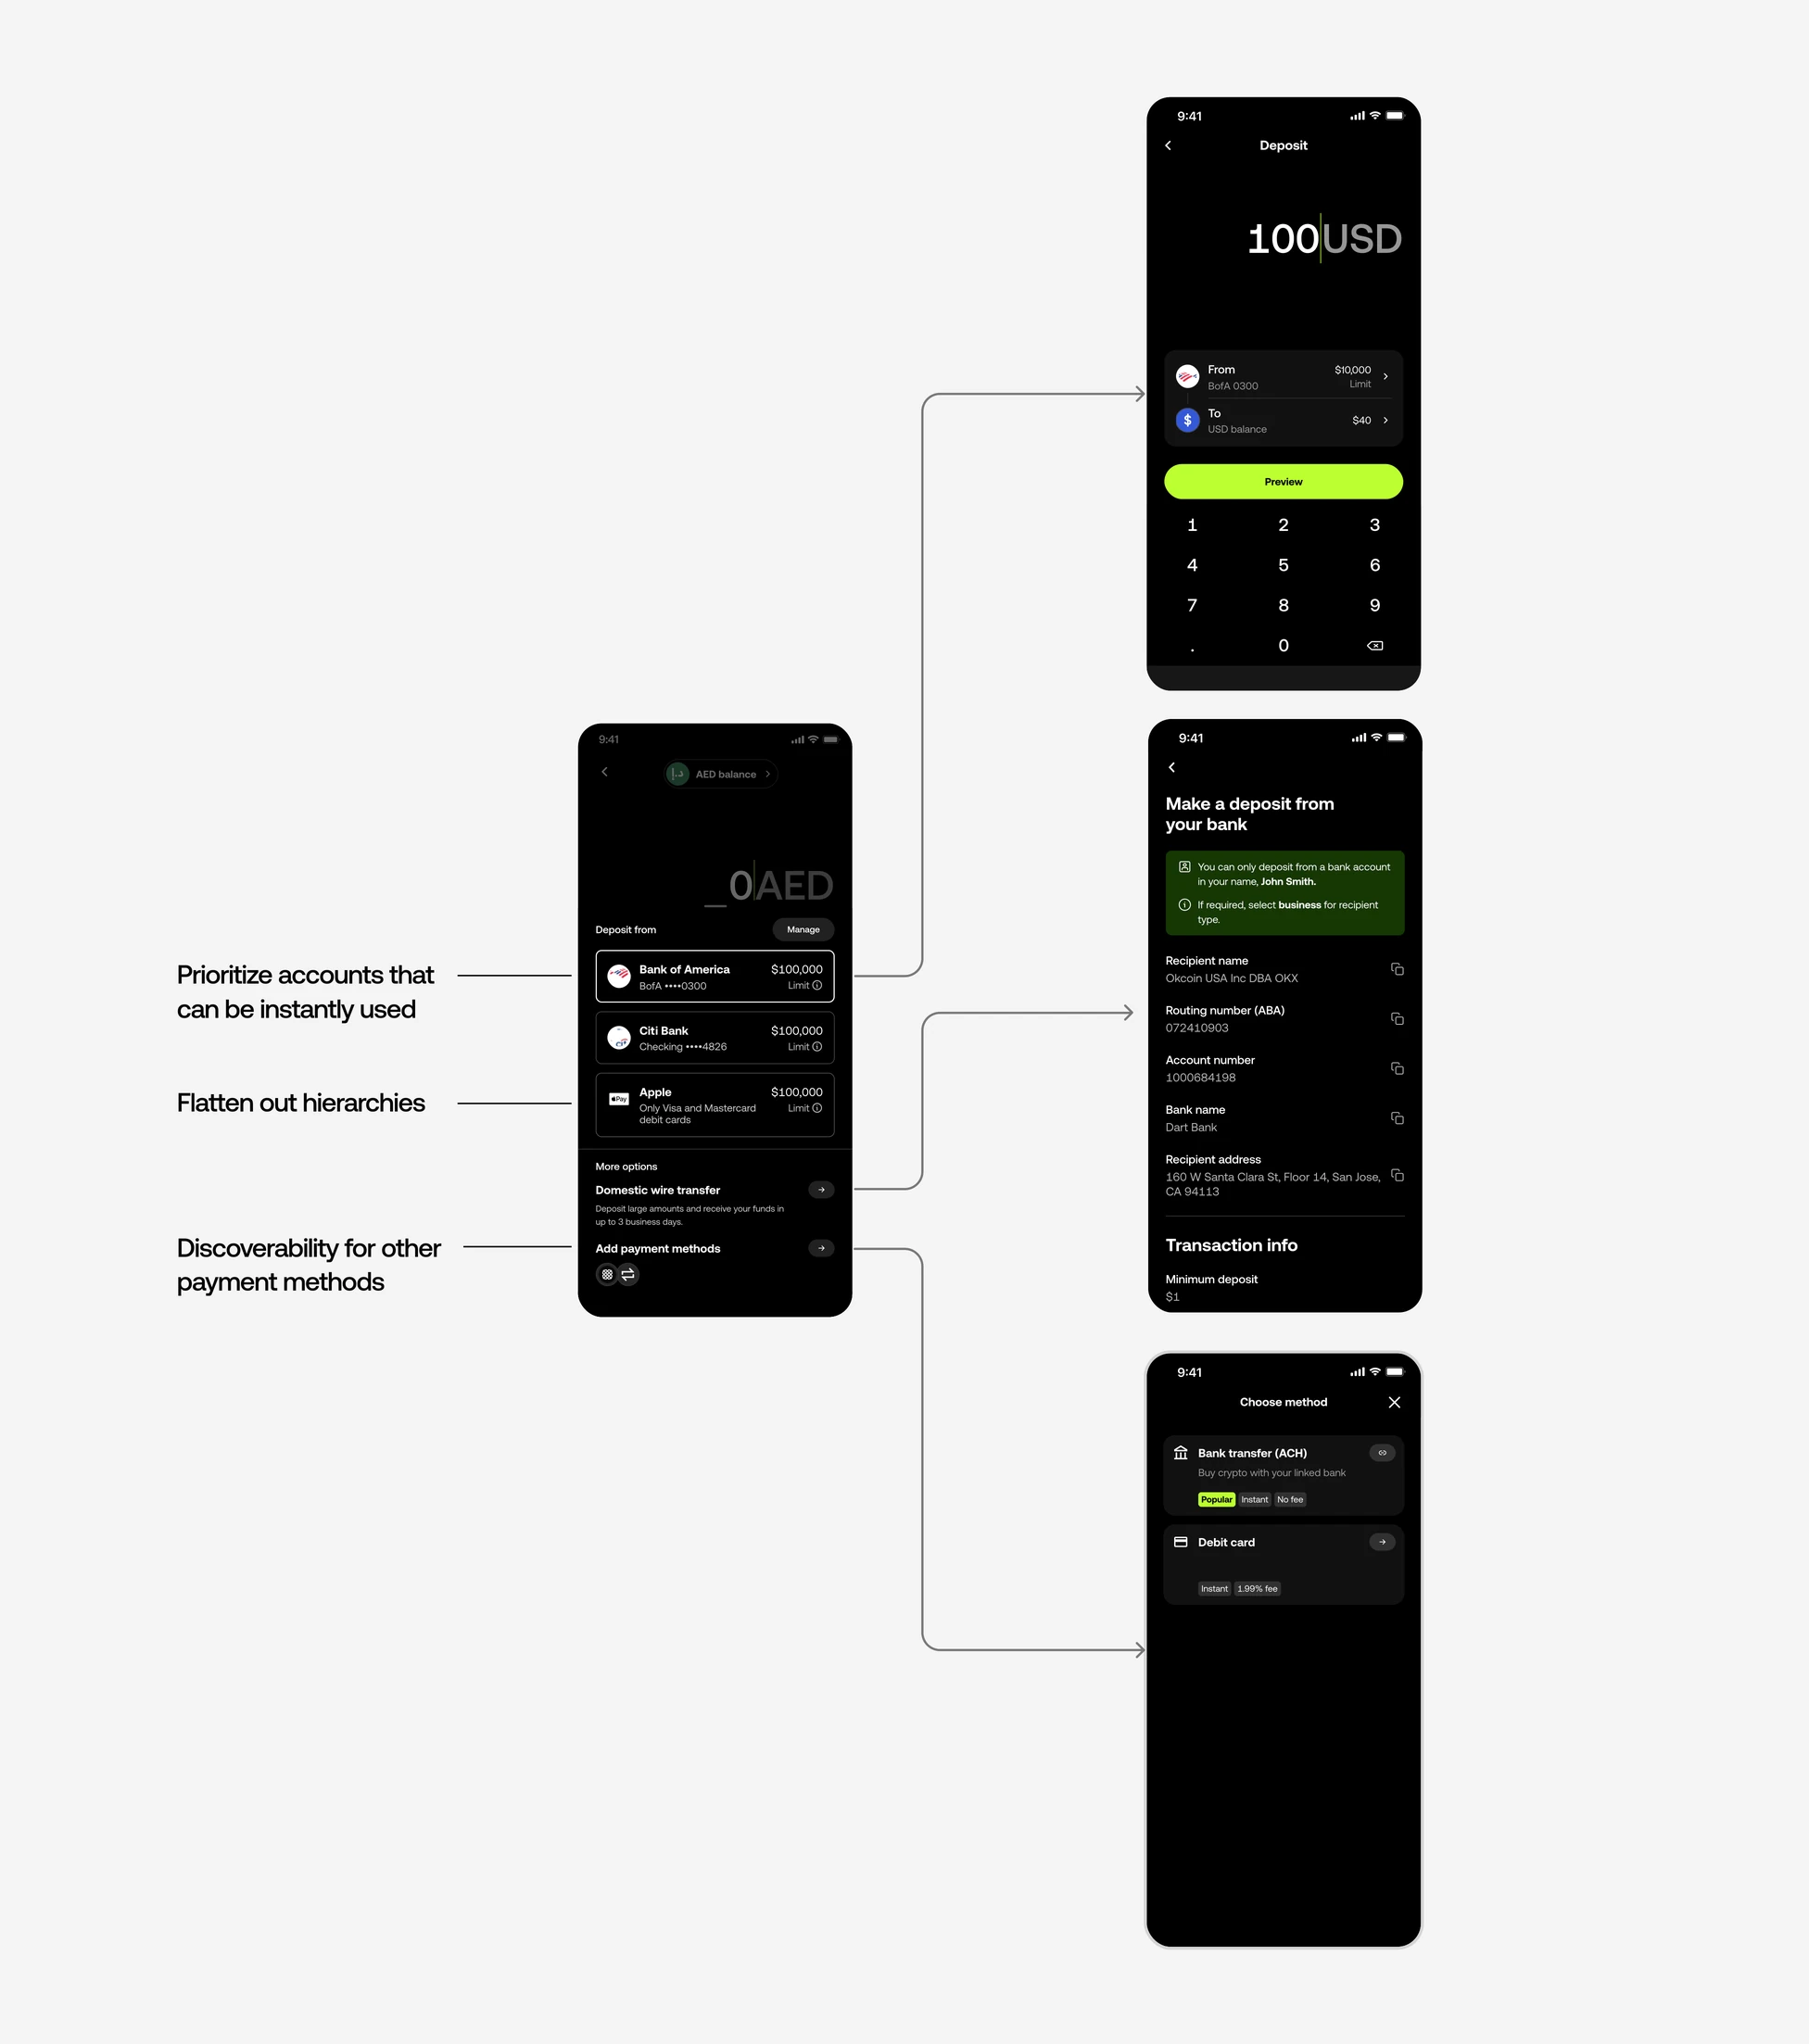
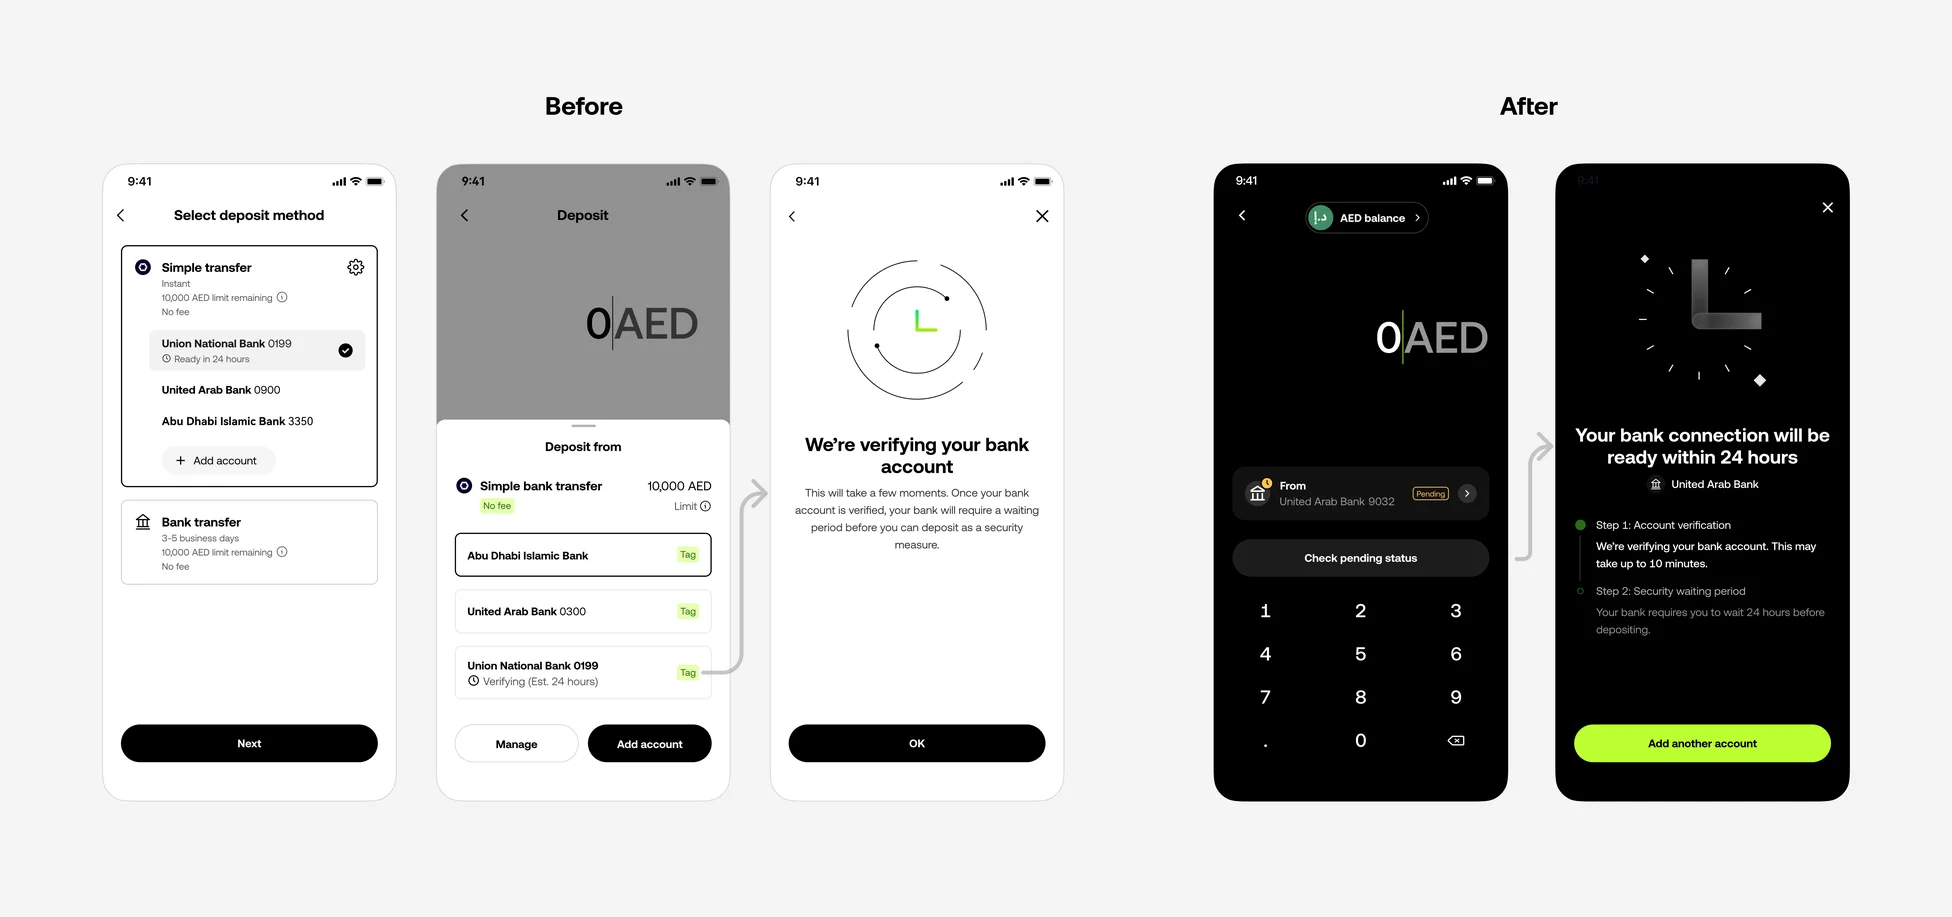
A pending account now remained visible during its 24-hour cooldown
Previously, a newly added UAE Simple Transfer account disappeared from the amount page during its cooldown. Users had to reopen the payment sheet to find its status.
In the new design, the account remained selected with a “Pending” label. The CTA changed to “Check pending status.”
Once the account became available, the CTA returned to Deposit.
One flow now covered different methods and account states
Users could enter an amount directly and manage every method from one sheet.
New markets could reuse the same structure for ready accounts, payment instructions, account setup, and pending states.
The combined release increased the use of direct payment methods
Within one month:
3×
Apple Pay usage
+60%
First-time card trades
The release included several onboarding and checkout changes, so these figures reflect the combined product update rather than one individual screen.